Kendall Miami Homes Buyer Guide: How Family and Suburban Buyers Should Shortlist (2026)
By Rangely Adames • September 28, 2026 • 10 min read
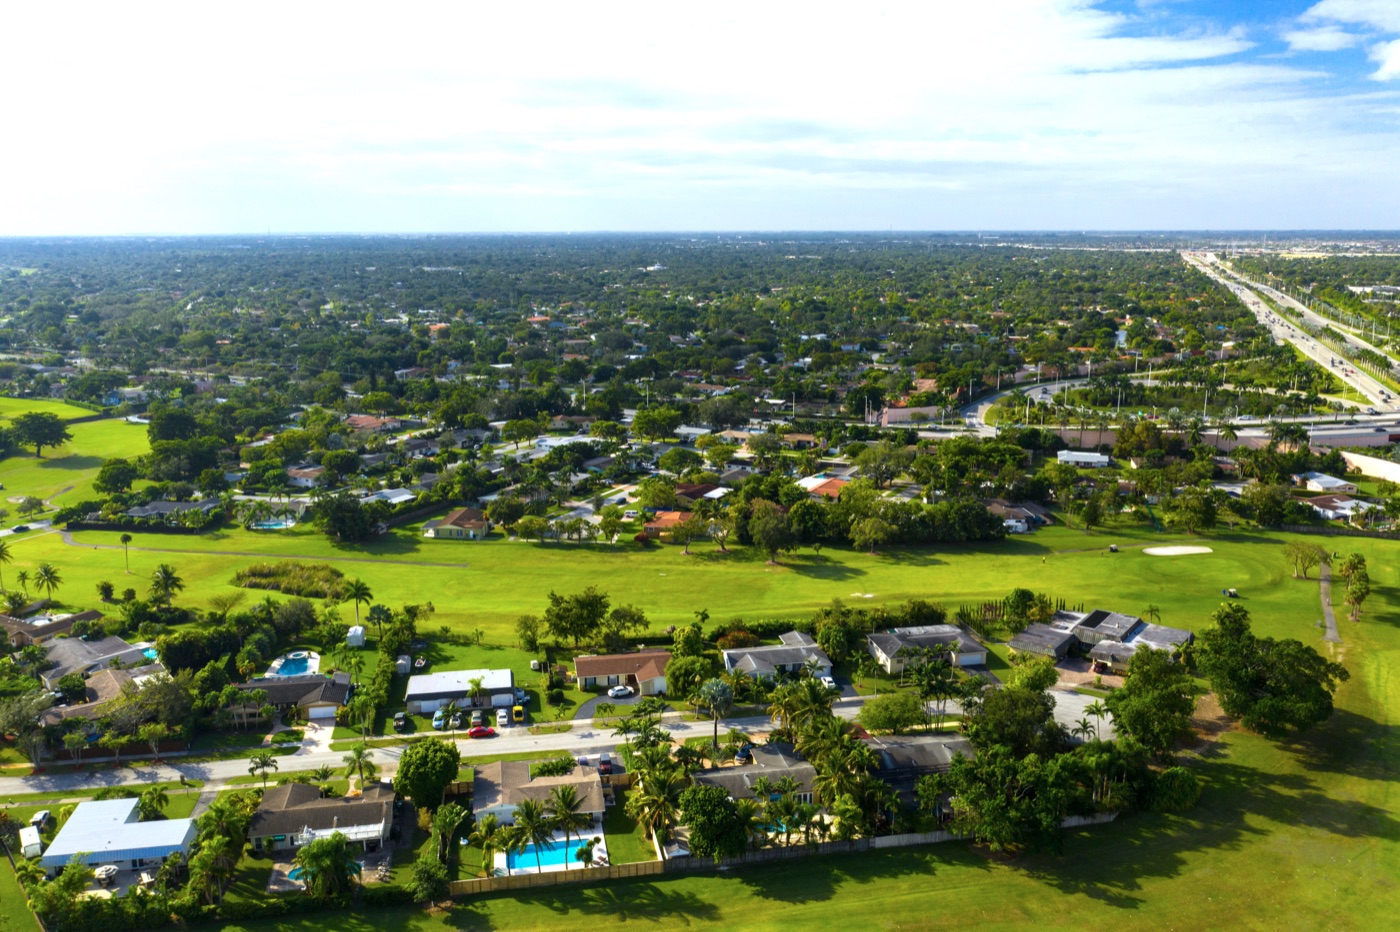
Kendall attracts buyers who want more space, a residential feel, and a routine that is not built around a Downtown tower. That appeal is real, but it is also easy to oversimplify. Two Kendall streets can feel completely different once you account for commute, lot size, HOA rules, noise, flooding questions, renovation quality, school logistics for your household, and the monthly cost of ownership beyond the purchase price.
I help family and suburban buyers shortlist Kendall homes with a practical filter instead of a long, unfocused search. We start with how you live, then narrow to home types and blocks that deserve a closer look. Hablamos Espanol.
This guide is educational, not legal, tax, insurance, lending, or school-admissions advice. Your Florida closing attorney, CPA, insurance professional, lender, inspector, surveyor, and any homeowners association must answer questions specific to your purchase. Listing language never replaces documents.
If you want a broader neighborhood overview of Kendall living themes, start with my live Kendall homes for sale guide. This article focuses on the shortlist process: what to decide first, what to compare next, and what to verify before an offer.
Building a Kendall shortlist for your family?
I help buyers compare commute, home type, HOA rules, condition, and closing logistics in English or Spanish. Hablamos Espanol. Call or WhatsApp (954) 833-0020.
Call (954) 833-0020The short answer: shortlist from lifestyle, then from the address
A useful Kendall search usually moves in this order:
- Define the household plan. Commute, bedrooms, outdoor space, pets, guests, work-from-home needs, and whether you need a quieter residential block or more commercial convenience nearby.
- Choose the property type that fits that plan. Single-family home, townhome, villa, or condo in a suburban setting each carry different rules, fees, parking patterns, and maintenance responsibilities.
- Compare the actual homes and associations. Condition, lot and drainage observations, roof and HVAC age clues, HOA or condo documents, insurance questions, and monthly ownership costs.
- Only then write an offer. Controllable contract dates, inspection scope, financing or cash readiness, and attorney review matter more than rushing because a listing looks popular.
A beautiful kitchen in a home that fails your commute, parking, HOA, or insurance fit is not a shortlist win. A plainer home that matches your routine and document review can be a stronger candidate.
Explore on rangelyadames.com
Start with how your household actually lives
Before we tour every available Kendall listing, I ask buyers to write down a short lifestyle brief. Keep it concrete:
- Who lives in the home full time, and who visits often?
- How many bedrooms and bathrooms are required versus preferred?
- Do you need a dedicated workspace, guest room, or multigenerational layout?
- How important are a yard, pool, garage, driveway parking, or outdoor storage?
- What is your daily route to work, clients, airports, or family in other Miami-Dade areas?
- Do pets, outdoor hobbies, or frequent deliveries change what a block needs to support?
- Are you relocating, upsizing, downsizing, or buying a first suburban home after renting?
These answers prevent a common Kendall mistake: treating every suburban listing as interchangeable because it sits west of Downtown. A family that needs a quiet cul-de-sac and yard space is shopping a different product from a household that wants quicker access to major corridors and errands. A remote worker may care more about interior noise, light, and reliable internet options than about a formal dining room.
If you are comparing suburban options across Miami-Dade, my Doral vs Kendall article and best Miami neighborhoods for families overview can help frame the lifestyle trade-offs. Use them as orientation, then bring the decision back to your own commute and household plan.
Decide whether you want a house, townhome, or suburban condo
Kendall inventory includes single-family homes, townhomes, villas, and condominium communities with a suburban character. The right category depends on maintenance preference, budget structure, and how much shared governance you want.
Single-family homes
A house can offer yard space, driveway convenience, and more control over renovations, subject to permits, setbacks, and any applicable association rules. It also means more owner responsibility for exterior systems, landscaping, drainage observations, fencing, pools if present, and many insurance questions. During showings, look past staging. Walk the lot edges, note drainage patterns after rain when possible, check for obvious roof, window, and exterior wear, and ask how the household would use the outdoor space on a normal week.
Townhomes and villas
Townhomes and villas can balance space with less exterior work than a freestanding house, but association rules, fees, parking assignments, and shared-wall realities matter early. Confirm what the association maintains, what the owner maintains, how guest parking works, and whether exterior changes require approval. Two units with similar interior photos can have different fee structures and rule sets.
Condos in a suburban setting
Some Kendall buyers prefer a condominium lifestyle with amenities and less exterior maintenance. In that case, treat the purchase like any condo file: association documents, reserves, insurance division, parking, rental rules if relevant, and unit condition all need review. My condo vs house in Miami guide is a useful companion when you are still deciding between ownership models.
Do not force a house search if your schedule and maintenance appetite point to a townhome or condo. Shortlisting starts with the ownership model you will actually enjoy.
Commute, errands, and the real weekday map
Suburban living only works if the weekly map works. When we shortlist Kendall homes, I ask buyers to test the commute at the hours they will actually travel, not only at midday. Consider:
- Morning and evening drive times to your workplace or client areas
- Access to the corridors you use most often
- School drop-off and pickup routes if that is part of your household plan
- Grocery, medical, and weekend errand patterns
- Airport or family visits elsewhere in South Florida
A home that looks ideal on a Saturday tour can feel different after a weekday commute test. If two shortlisted homes are otherwise close, the better daily route often decides the winner.
I do not invent commute times as fixed facts in this guide because traffic changes by hour, season, construction, and destination. Your own timed drive or transit trial is the evidence that matters.
What to compare once a home enters the shortlist
Once a Kendall property survives the lifestyle and property-type filter, evaluate it with a structured checklist.
Condition and systems
Ask about or observe:
- Roof age clues, prior permits, and visible exterior wear
- HVAC age, service history, and thermostat zones if present
- Plumbing fixtures, water pressure, water heater condition, and signs of past leaks
- Electrical panel observations and renovation quality
- Windows, doors, weather sealing, and hurricane-protection features where installed
- Kitchen and bath age versus true function
- Pool equipment, fencing, and outdoor electrical if applicable
- Evidence of moisture, staining, or prior repairs that an inspector should review
A licensed home inspector evaluates condition. A specialist may be needed for roof, pool, sewer, or other focused questions. My role is to help you sequence the right questions early so deadlines are usable.
Lot, drainage, and outdoor usability
For houses especially, outdoor space is part of the product. Look at how water moves after rain when timing allows, how the yard is used, fencing and privacy, tree proximity to structures, and whether the outdoor areas support your actual plans. Survey and title questions belong with the professionals on your closing team.
HOA or condo governance
If the property sits in an association, request the documents your attorney and lender identify as relevant. Depending on the community, that may include rules, budgets, reserves, meeting minutes, insurance information, application procedures, pet policies, leasing rules, parking rules, and any disclosed assessments or capital projects. Do not rely on a neighbor summary or listing remark as the final answer.
Monthly ownership costs beyond the price
Build a category list, not a guess at someone else's numbers:
- Principal and interest if financing, or opportunity cost framing if cash
- Property taxes as quoted by your professionals for the specific parcel assumptions they use
- Homeowners insurance and any required separate coverages
- HOA or condo fees and what they include
- Utilities, landscaping, pool care, and routine maintenance
- Closing costs and prepaid items discussed with your lender and title company
My Miami closing costs explained article gives vocabulary for transaction categories. Your lender, title company, and closing attorney provide file-specific figures.
Schools and family logistics without invented rankings
Many Kendall buyers care about school logistics. Treat that topic carefully. School options, boundaries, programs, and transportation can change, and household needs differ. I do not invent school rankings, ratings, or admission outcomes as facts in marketing copy.
A better shortlist process is:
- Identify the schools or program types your household is actually considering.
- Confirm current boundary and application information from official school sources.
- Test the morning and afternoon route to those locations from each shortlisted home.
- Ask how after-school care, activities, and sibling logistics would work from that address.
If schools are a primary driver, put the official confirmation step early so you do not fall in love with a home that fails the route or eligibility plan your family needs.
Financing, cash, and offer readiness
Cash and mortgage buyers can both succeed in Kendall, but the readiness checklist differs. A financed buyer should speak with a lender early about documentation, reserves, condo or association project questions if applicable, and timeline. A cash buyer still needs title, inspection, insurance, survey where required, and contract diligence.
My cash versus mortgage guide for Miami buyers covers high-level trade-offs. For sequence and deadlines, use the Miami buyer closing timeline. Title questions are covered in the Florida title insurance guide.
When you are ready to write an offer, we discuss comparable information your licensed real estate professionals can evaluate, inspection periods, association review if any, financing terms, deposit timing, included personal property, and closing date. I do not justify a purchase with invented appreciation, median-price claims, or ROI projections. A Kendall home should fit your housing plan and document review, not a speculative spreadsheet promise.
Remote buyers and bilingual coordination
You do not have to live in Miami already to buy in Kendall. Remote buyers can use live video tours, focused follow-up video, inspection coordination, and a clear communication plan around contract dates. If you cannot attend closing, discuss signing options early with your closing attorney and title company. My remote Miami purchase and POA closing guide explains the coordination themes at a high level. The legal signing path for your file still belongs to counsel and title.
I work in English and Spanish and coordinate with the specialists your transaction needs. Hablamos Espanol. Buyers relocating from elsewhere in Florida, other U.S. states, or abroad can use the same shortlist method: lifestyle first, property type second, document and condition review third.
For a full step-by-step purchase overview beyond Kendall, use the Miami Buyer's Guide. Neighborhood orientation across Miami and Fort Lauderdale also lives on the neighborhoods index.
A practical Kendall shortlist checklist
Use this list before you expand the tour schedule:
- What is the household use: primary home, relocation, upsizing, or multigenerational living?
- Which property type fits maintenance appetite: house, townhome/villa, or condo?
- Which commute and errand routes must work on a normal weekday?
- How many bedrooms, bathrooms, parking spaces, and outdoor features are non-negotiable?
- Which HOA or condo rules would eliminate a community immediately?
- What inspection and insurance questions matter most for the homes you like?
- Are financing pre-approval or cash proof ready before a competitive moment?
- Who on the professional team handles attorney review, title, lender, and inspection?
- If buying remotely, who handles access, signatures, and key handover?
- Which two or three homes truly deserve a second visit instead of twenty first visits?
Mistakes to avoid when shortlisting Kendall homes
- Touring endlessly without a written lifestyle brief
- Choosing a house because of staging while ignoring commute and parking
- Treating HOA fees as optional reading
- Skipping an inspection because the home "looks updated"
- Assuming every suburban block has the same flood, insurance, or drainage profile
- Using invented school rankings or market medians as your decision engine
- Waiting to talk to a lender until after you find "the one"
- Wiring funds from an email without verifying instructions by phone with the title company
- Comparing only list price and ignoring monthly ownership categories
- Expanding the shortlist so wide that every showing feels the same
Ready to shortlist Kendall homes with a clear plan?
Kendall can be an excellent fit for family and suburban buyers when the search is structured. We can define your household plan, narrow the property type, compare a focused set of homes, and coordinate the diligence that belongs to inspectors, lenders, title professionals, and your closing attorney.
I work with buyers in English and Spanish. Hablamos Espanol. Call or send a message with your target move timing, must-have features, commute anchors, and whether you prefer a house, townhome, or condo setting.
Let's build your Kendall home shortlist
Tell me your household plan, property type preference, budget range, and timing. I will help you compare Kendall options clearly in English or Spanish. Call (954) 833-0020 or send a message to get started.
Related Articles
September 28, 2026 · 10 min read
Argentine Buyers Guide to Miami Real Estate: Process, Financing Themes, and Neighborhood Fit (2026)
Buying Miami real estate from Argentina is workable when you separate what your agent coordinates from what your attorney, CPA, and lender decide. This support guide walks through the process, financing themes, remote closing, and neighborhood fit, then points you to the Argentina foreign-buyer hub for next steps.
Read article →February 2026 · 9 min read
Aventura Real Estate Guide: Condos, Schools & Lifestyle (2026)
Luxury high-rises, top-rated schools, and the Aventura Mall — why families and investors love this North Miami suburb.
Read article →February 2026 · 9 min read
Airbnb Investment Properties in Miami: Rules, ROI & Best Areas
Short-term rental regulations, income projections, and the best Miami neighborhoods for Airbnb investing.
Read article →